Systems
The Interest Rate and the Oak
A discount rate is a quiet rule that can make an eighty-year tree look irrational
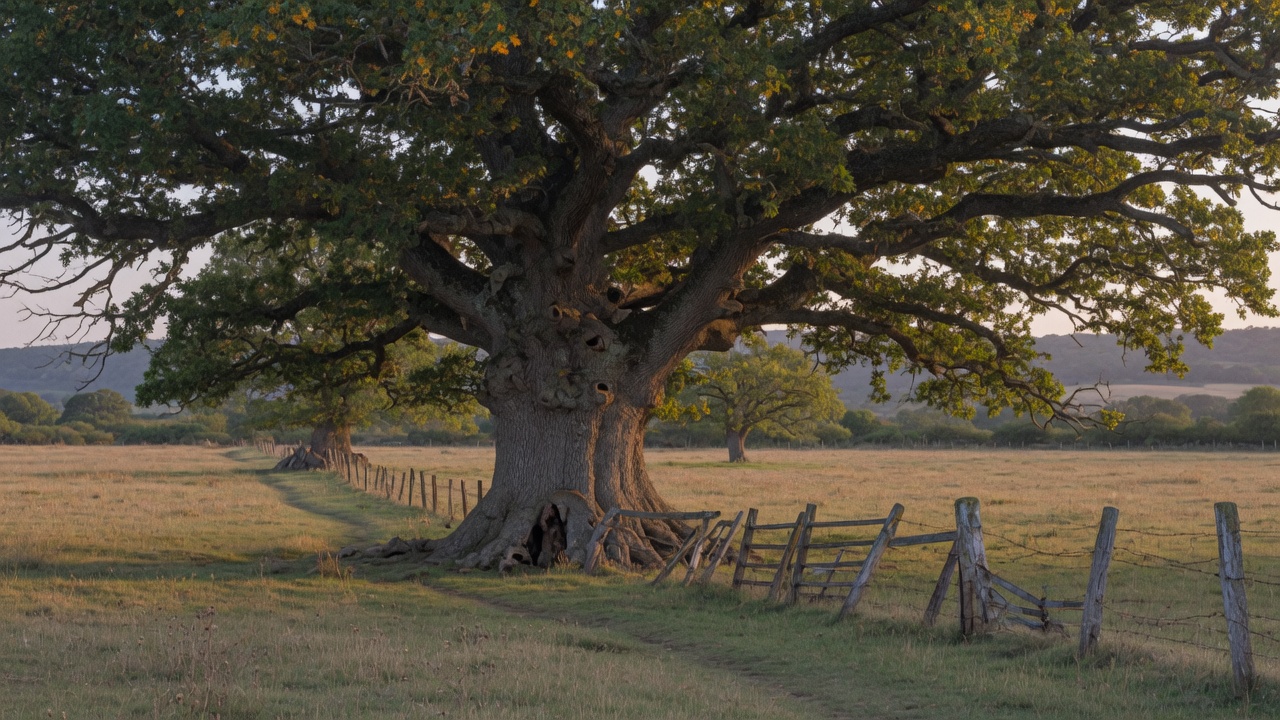
An oak is expensive only if the future is cheap.
A large tree is a century of water, carbon, shade, and habitat standing in one place. A spreadsheet asked to compare that tree with a parking structure will, if it uses a familiar commercial discount rate, make the distant years almost vanish. The parking structure earns soon. The oak earns slowly, and some of what it earns was never given a column.
This is not a conspiracy. Discounting is how loans, pensions, and public works stay internally consistent. It is also how a civilization can liquidate a forest in language that sounds like prudence. The force is invisible because it lives in a percentage, not in a chainsaw.
A clock inside a number
A discount rate is a conversion. It says how many future dollars, lives, tonnes, or hours of shade are worth one of the same thing today. At 7 percent real, a benefit of one hundred in thirty years is worth about thirteen today. At 3 percent it is worth about forty. At 1 percent it is worth about seventy-four. At 0.1 percent it is still ninety-seven. The arithmetic is not in dispute. The clock is.
Private finance uses rates that reflect opportunity cost, risk, and the impatience of people who will not live forever. That is appropriate for a loan. It is a different question whether a government, counting goods that last longer than a career, should use the same clock. Cost–benefit analysis, as practiced in public agencies, has to pick something. The pick is often treated as a technicality, like a depreciation schedule. It is closer to a theory of who counts.
The Ramsey formula, which still organizes much of the academic argument, writes the social discount rate as the sum of two ideas. One is pure time preference: how much less a future person’s welfare is worth simply because it is future. The other is the declining extra value of consumption if later people are richer—an inequality adjustment across time. Multiply that second term by expected growth, add the first, and you have a rate. Change either ingredient and the present value of a slow ecological good can swing by a factor of ten.
There is no laboratory result that tells you the moral ingredient. A chemist can measure lead in gasoline. An economist cannot measure whether a child born in 2126 should be weighted at 0.1 percent a year less than a child born now, or at 3 percent, or at zero. The formula can be written with Greek letters. The letters still contain a judgment.
What the United States has used
For two decades after 2003, the U.S. Office of Management and Budget’s Circular A-4 told agencies to discount regulatory benefits and costs at 3 percent and at 7 percent. The 3 percent was offered as a social rate of time preference, inferred from the real return on government bonds. The 7 percent was offered as an approximation of the pretax return on private capital. Many analyses reported both. A climate or public-health rule that looked justified at 3 percent could fail at 7 percent, or look marginal at both.
The 3-and-7 pair was not a discovery about nature. It was a convention that froze a particular reading of late-twentieth-century U.S. capital markets and then applied it, sometimes for a century, to problems those markets do not price. Old-growth, climate stability, a levee’s residual risk in year eighty, a nuclear-waste canister: all of these were asked to compete with a parking structure on a clock calibrated to office buildings and equipment.
In November 2023, OMB issued a revised Circular A-4. The default near-term social rate of time preference was set at 2.0 percent, based on a thirty-year average of yields on ten-year Treasury securities, using Treasury Inflation-Protected Securities where available, then adjusted so that inflation is measured by the personal consumption expenditures index rather than the consumer price index. The old 7 percent capital rate was no longer the paired default. For long horizons, the Circular provided a declining schedule: 2.0 percent through 2079, then stepping down, in the published appendix, to 1.1 percent in the 2160s. The appendix is to be updated every three years.
That revision was described, by the administration that issued it, as an update of the 2003 method with newer data, not as a philosophical conversion. Real rates had been lower for a long stretch than the 2003 guidance assumed. A comment letter from a large group of economists called the direction well justified. Critics argued that a 2 percent default, especially after the inflation of 2021–2023, would overstate the present value of distant benefits and understate the opportunity cost of crowding out private investment. Both sides were talking about the same lever. They disagreed about what the lever is for.
The 2023 Circular also discussed, then largely stepped back from, using the Ramsey formula as an official alternative for long-term rates. The declining schedule that remains is closer to a Weitzman–Gollier argument than to a sermon: if future rates are uncertain and some of that uncertainty persists, the certainty-equivalent rate used today should fall as the horizon lengthens. France and the United Kingdom had already used declining schedules in public appraisal. In 2013, a panel that included Kenneth Arrow, Maureen Cropper, Christian Gollier, William Nordhaus, Martin Weitzman, and others wrote in Science that the theoretical case for a declining certainty-equivalent rate was compelling, and that it would raise estimates of the social cost of carbon by as much as two- or threefold relative to a constant 4 percent.
The United Kingdom’s Green Book and France’s public-investment guidance had already put declining rates into official practice, on the ground that distant years should not be crushed by a constant exponential as if we knew the return on capital in 2150 as well as we know it next Tuesday. OMB’s 2023 schedule is a late American cousin of that idea, not a rupture with economics.
Notice what even this consensus does not do. It does not produce a unique moral rate. It says that uncertainty about the future of the economy is a reason not to treat year 150 as if it were year 15 with more compounding. An oak that lives 150 years is precisely the kind of object that distinction was built for.
A worked example makes the clock less abstract. Suppose an urban oak will deliver, in some incomplete accounting, a thousand dollars a year of shade, stormwater, and amenity for a century, and that a surface parking lot will deliver three thousand a year for thirty years and then need to be rebuilt. At 7 percent, the parking lot’s near cash dominates; the oak’s later decades are a rumor. At 2 percent, and still more on a declining schedule, the oak’s long stream is allowed to speak. Change the columns—add habitat that was never priced, or a carbon tonne that a parking lot does not store—and the ranking can flip even before the rate moves. “Uneconomic” in the first run was a joint product of a high clock and a thin ledger. Neither is a law of trees.
Stern and Nordhaus, fairly
In 2006 the British government published the Stern Review on the economics of climate change. Its headline claim—that the costs of inaction could be equivalent to losing 5 percent of global GDP, now and forever, and perhaps as much as 20 percent if a wider range of risks was included—was unlike most of the integrated-assessment literature that had preceded it. The Review recommended early, substantial mitigation, on the order of 1 percent of world GDP.
William Nordhaus, whose DICE model had for years been the most visible economic framework for climate policy, argued in Science in 2007 that the Review’s drama came “almost entirely” from its discounting, “only marginally” from new science or economics. Stern had set pure time preference at 0.1 percent per year, justified mainly as an allowance for the chance that humanity might not be here, and had set the elasticity of marginal utility at 1. With consumption growth around 1.3 percent, the implied social discount rate was about 1.4 percent. Nordhaus’s own calibrations, aiming to respect observed returns on capital, produced a consumption discount rate in the neighborhood of 4 to 4.5 percent, with a pure time-preference rate on the order of 1.5 percent. In DICE, swapping Stern’s discounting into Nordhaus’s model raised the social cost of carbon dramatically. Nordhaus’s preferred path was a “climate ramp”: modest prices now, rising later. Stern’s path was immediate and steep.
Nordhaus’s objection was not that future people do not matter. It was that a near-zero pure rate of time preference, combined with a low elasticity, implied savings behavior and interest rates that do not match the world we live in. If society truly valued the future as Stern’s parameters did, we would already be investing at a much higher rate in ordinary capital, and market returns would be lower. Using a rate that the capital market does not display, he argued, would select climate projects with negative net present value relative to other investments that could also help future people—education, health, infrastructure. The Review, on this view, was not so much valuing the future as refusing to look at the opportunity cost of valuing it that way.
Stern’s reply, in the Review and afterward, was that climate change is not an ordinary investment. It is a one-way transfer of risk onto people who cannot bargain with us. Market rates reveal the impatience and the risk-bearing of people who are alive, in incomplete markets, with finite lives. They do not reveal an ethical weight across generations. Frank Ramsey himself, in 1928, had called discounting later generations’ welfare “ethically indefensible,” a practice that “arises merely from the weakness of the imagination.” Stern treated a tiny pure rate as a gesture at extinction risk, not as a preference for the present. If later people are richer, the inequality term in Ramsey’s formula still discounts their consumption; Stern did not set that term to zero. He declined to add a further penalty for being born late.
Both positions are coherent. Neither is a measurement. Partha Dasgupta criticized Stern from another angle, arguing that if you care as much about inequality as a low pure rate implies, you might want a higher elasticity of marginal utility, which would raise the discount rate when growth is positive and complicate the Review’s conclusions. Other economists, including Nicholas Stern in later writing, have stressed that damages, climate sensitivity, and the shape of the damage function also move results, and that pinning the entire gap on a single parameter is too neat. A 2015 paper in the Proceedings of the National Academy of Sciences by Antony Millner and Geoffrey Heal put the disagreement where it belongs: not in arithmetic, but in whose discount rate, and on what authority.
Flying River will not award the gavel. The honest statement is that two serious research programs, using related models, produced different clocks, and that the clocks—not a secret about the physics—did much of the work of producing different policies. A reader who treats Nordhaus as a villain for using market information is not reading him. A reader who treats Stern as a sentimentalist for refusing to let observed impatience settle an intergenerational question is not reading him either.
What high rates do to slow goods
The oak is a pedagogical object, not a unique one. Any good whose yield is stretched across many decades will look worse as the rate rises: an old-growth stand, a restored wetland, a durable public building, a climate trajectory that avoids a tail risk in 2150, a species whose recovery takes a generation of breeding. Conversely, any cost that is paid late—decommissioning, sea-level rise, a cancer with a long latency, a flood that arrives after a map has been out of date for thirty years—will look smaller.
This is mechanical. It does not require bad faith. An analyst who writes “uneconomic” after applying 7 percent to a forest’s non-timber yield may be doing the assignment exactly as written. The word still conceals a clock. It conceals, too, the goods that never entered the cash flow: habitat that has no owner, shade that is not billed, a childhood spent under a canopy that will not be there. Missing columns and a high rate work in the same direction. Together they can make a parking lot look like the only adult option.
There is a further, quieter effect. High rates do not merely shrink the future. They reshape which future is even admitted to the comparison. A project whose benefits arrive as a thin stream for a century will lose to a project whose benefits arrive as a lump in year five, even if the undiscounted sums run the other way. Land conversion follows those numbers even when the ecological goods were never priced. “The market decided” often means “we chose a clock, and then we omitted the columns that would have made the clock less decisive.”
Declining rates, lower social rates, and separate moral constraints are three different responses. A declining schedule says: do not pretend you know the rate in year 120 as well as you know it in year 10. A lower social rate says: public time is not private impatience. A constraint says: some goods are not for sale at any discounted price—an endangered species, a human life in a cost–benefit table that has already been asked to do too much, a sacred grove. Each response can be abused. A zero rate would justify almost any present sacrifice for a perpetual trickle. An infinite rate would justify almost any present consumption. The interesting work is in the middle, and the middle is a political and ethical argument that happens to be written in percentages.
No correct moral rate
It would be satisfying to end with a number. Flying River will not manufacture one.
What can be said without theatre is more limited, and more useful.
First, discounting is not optional in any analysis that compares goods across time. Refusing to discount is itself a rate: zero. Zero is a position, not a refusal to have a position.
Second, the rate that is appropriate for a private portfolio is not automatically the rate that is appropriate for a public ecological good. Mixing them is a choice. So is separating them. Circular A-4’s long experiment with 3 and 7 percent, and its later move toward 2 percent and a declining tail, are evidence that even a cautious bureaucracy knows the clock is not a constant of nature.
Third, uncertainty about growth and about the rate itself is a reason, widely accepted among the economists who argue about this for a living, to let the certainty-equivalent rate fall as the horizon lengthens. That is not sentiment. It is an averaging argument. The oak lives in the lengthened horizon.
Fourth, when a restoration, a park, or an old stand is called uneconomic, the interesting question is not whether the analyst can arithmetic. It is which future was counted, at what discount, and whose. An interest rate is a theory of care. It can be revised without abandoning math.
Fifth, climate is the loud case, not the only case. Nuclear waste, coastal setbacks, a levee’s residual risk, a breeding program that takes thirty years to put a bird back on a cliff: all of them live in the tail of the discount function. Weitzman’s argument about fat tails—that a small chance of a ruinous outcome should not be shrunk to a footnote by a high rate—is a cousin of the oak, not a replacement for it. You do not need a catastrophe to need a clock that can see a century. You only need a good that will still be doing work when the people who approved the spreadsheet are dead.
The oak does not know the federal funds rate. It only knows whether it is still allowed to stand while the numbers finish their sentence. A civilization that wishes to keep such objects will have to notice the sentence. Not because a campaign has declared interest rates to be a plot. Because a percentage is a hidden force, and hidden forces are this publication’s subject. Follow the connection far enough and “uneconomic” is not a verdict on a tree. It is a verdict on a clock. Clocks can be wrong for ethical reasons even when they are right for arithmetic ones. That is not a paradox. It is the ordinary condition of using numbers to speak about people who are not yet in the room.
Sources
- Office of Management and Budget. Circular No. A-4, “Regulatory Analysis.” 17 September 2003; revised 9 November 2023.
- Office of Management and Budget. Circular No. A-4 Appendix, “Default Social Rate of Time Preference Estimates.” 9 November 2023.
- Office of Management and Budget. “Current and Historical Estimates of the Social Rate of Time Preference.” 9 November 2023.
- White House Office of Management and Budget. “Biden-Harris Administration Releases Final Guidance to Improve Regulatory Analysis.” 9 November 2023.
- Stern, Nicholas. The Economics of Climate Change: The Stern Review. Cambridge: Cambridge University Press, 2007. (Pure rate of time preference 0.1 percent; elasticity of marginal utility 1; implied social discount rate near 1.4 percent.)
- Nordhaus, William D. “A Review of the Stern Review on the Economics of Climate Change.” Journal of Economic Literature 45, no. 3 (2007): 686–702.
- Nordhaus, William D. “Critical Assumptions in the Stern Review on Climate Change.” Science 317, no. 5835 (2007): 201–202.
- Dietz, Simon, and Nicholas Stern. “Why Economic Analysis Supports Strong Action on Climate Change: A Response to the Stern Review’s Critics.” Review of Environmental Economics and Policy 2, no. 1 (2008): 94–113.
- Millner, Antony, and Geoffrey Heal. “Agreeing to Disagree on Climate Policy.” Proceedings of the National Academy of Sciences 111, no. 10 (2014): 3695–3698.
- Arrow, K., M. Cropper, C. Gollier, B. Groom, G. Heal, R. Newell, W. Nordhaus, et al. “Determining Benefits and Costs for Future Generations.” Science 341, no. 6144 (2013): 349–350.
- Weitzman, Martin L. “Why the Far-Distant Future Should Be Discounted at Its Lowest Possible Rate.” Journal of Environmental Economics and Management 36, no. 3 (1998): 201–208.
- Weitzman, Martin L. “On Modeling and Interpreting the Economics of Catastrophic Climate Change.” Review of Economics and Statistics 91, no. 1 (2009): 1–19.
- Gollier, Christian, and Martin L. Weitzman. “How Should the Distant Future Be Discounted When Discount Rates Are Uncertain?” Economics Letters 107, no. 3 (2010): 350–353.
- Ramsey, F. P. “A Mathematical Theory of Saving.” Economic Journal 38, no. 152 (1928): 543–559.
- HM Treasury. The Green Book: Central Government Guidance on Appraisal and Evaluation. London: HM Treasury (declining long-term discount rates in UK public appraisal).
- Dasgupta, Partha. “Commentary: The Stern Review’s Economics of Climate Change.” National Institute Economic Review 199 (2007): 4–7.
An oak is expensive only if the future is cheap.
Follow the connection
- Discount rate
- Present value
- Short horizon
- Land conversion
- Lost future shade
What we know
- Discounting is standard in finance and in many public cost–benefit analyses: a benefit next year counts for less than a benefit today.
- High discount rates shrink long-lived goods—old trees, climate stability, infrastructure that lasts—relative to quick returns.
- Land conversion often follows those numbers even when the ecological goods were never priced.
What remains uncertain
- Which rate a society “should” use is a moral and political question, not a measurement.
- How much any one rate explains a particular clear-cut versus timber prices, zoning, and taste.
- Whether alternative accounting (lower rates, separate moral constraints) changes outcomes in practice.
What can we do?
You don't have to care about this because everyone else does. You can care because the evidence gives you a reason to.
- When a project is called uneconomic, ask what rate made the future small.
- Support land decisions that treat some goods as not for sale at any discounted price.
- Notice that “the market decided” often means “we chose a clock.”
Demonstration authors are fictional. The phenomena discussed are real subjects of public scientific literature and reporting. Sources named in the article are documented; this is not a comprehensive literature review.